Foodservice Operator Support Center
Our Support Center has everything Operators need to remain connected. Weekly Commodity Reports, Supply Chain Hot Takes, and Produce Alerts – ready to review!
Commodities Snapshot Report
For the week of October 5, 2026
Quickly review the latest weekly snapshot on all major commodities!
And for a deeper dive, scroll to the CommodityONE Reports below.
There’s no commodity update this week, but we’ll be back next week with fresh insights to keep your operation one step ahead!
-
Grains
Chicken production stayed in check last week. Young bird slaughter fell 2% from the prior week and was 2% below the same week last year. For the week ending September 26, output rose nearly 4% week over week but was down 1.4% year over year, and 2026 year-to-date weekly production is running just 1.4% ahead of last year. Monthly output has been coming in above the USDA's weekly estimates, though. August production was a solid 3.3% above last year, on a similar year-over-year gain in slaughter. The six-week average for chick placements is about even with last year, so production should stay tempered through at least the rest of October. Even so, many chicken markets were lower last week, including breasts, wings, and leg quarters. Table egg markets were up slightly.
Outlook: The USDA forecasts Q4 chicken output 2.3% above 2025, and nearly everyone expects output growth to stay tempered this fall. Several major chicken markets usually decline this month, including breasts and tenders. Tenders have been lower in October than in September in 10 of the last 11 years.
-
Beef
Beef output jumped 13.2% from the previous week, when operational disruptions interrupted production, but was still 2.8% below the same week last year. Late in the week, cattle imports from Mexico picked up to an estimated 7,000-plus head, the most in well over a year. Markets were mixed. They firmed early as slaughter tried to recover, then softened as the week went on. For the week, USDA Choice and Select boxed beef cutouts each gained less than 1%. Ribs and Select briskets led the gainers. Flanks stayed soft and are down more than 7% over the last four weeks. Beef 90 trim was lower, and the rest of the trim markets were higher. The Mexico imports are encouraging, but domestic cattle supplies still need to improve. Pasture conditions, which herd development depends on, remain historically poor: just 19% of pasture was rated good or excellent last week, the lowest for that week in more than three decades.
Outlook: Beef production is expected to run about 3% below last year this fall. The National Weather Service expects drought conditions in cattle country to improve over the coming months, which could build much stronger herd expansion momentum as the new year gets underway.
-
Dairy
CME spot dairy trading was light on Friday, with just 14 loads changing hands. For the week, CME cheese blocks and butter were lower, while dry whey and nonfat dry milk held firm. The nonfat dry milk weekly average climbed to a 19-week high and is within a dime of a multi-decade high. Constrained production has kept nonfat dry milk supplies limited. Domestic buyers are limiting purchases, but export demand remains solid. Butter has solid domestic demand, and export sales are outpacing it. Cheese markets traded at their lowest levels since 2020, weighed down by strong milk and cheese production and historically large cheese stocks. At the end of August, U.S. cold storage cheese inventory was 2.3% above a year ago, the largest in three years and the fourth largest on record.
Outlook: U.S. cheese is trading at its steepest discount to the E.U. since February, which should encourage exports. Further downside risk for cheese prices could be nominal.
Click Show More to view Poultry, Pork and Seafood.
-
Poultry
Chicken production stayed in check last week. Young bird slaughter fell 2% from the prior week and was 2% below the same week last year. For the week ending September 26, output rose nearly 4% week over week but was down 1.4% year over year, and 2026 year-to-date weekly production is running just 1.4% ahead of last year. Monthly output has been coming in above the USDA's weekly estimates, though. August production was a solid 3.3% above last year, on a similar year-over-year gain in slaughter. The six-week average for chick placements is about even with last year, so production should stay tempered through at least the rest of October. Even so, many chicken markets were lower last week, including breasts, wings, and leg quarters. Table egg markets were up slightly.
Outlook: The USDA forecasts Q4 chicken output 2.3% above 2025, and nearly everyone expects output growth to stay tempered this fall. Several major chicken markets usually decline this month, including breasts and tenders. Tenders have been lower in October than in September in 10 of the last 11 years.
-
Pork
Pork output rose 0.5% from the prior week but was 2.3% below 2025, and year-to-date weekly production is now 0.1% behind last year. Markets were mixed, with many at historically low levels. The cutout fell 1.4%, and ribs, loins, and hams were lower with it. The major pork trim markets also declined, with 42s at their lowest since May. History suggests more trim declines may be coming: the 42 trim market has averaged lower in October than in September in eight of the last nine years. Pork supplies have been limited this year despite heavier hog weights, and that trend looks set to continue this fall. Late last month, the USDA updated its March through May 2026 pig crop to 0.4% below the previous year, the smallest for that period since 2022. Those pigs come to slaughter this fall, and the USDA projects Q4 pork output at well under 1% above 2025.
Outlook: Limited supply and already-low prices could temper the usual seasonal decline in some pork markets over the coming weeks, including bellies. The USDA pork belly primal has averaged lower in December than in September in each of the last seven years.
-
Seafood
Frozen Alaskan pollock filet slipped just 2% month over month in the July data and continues to track cod closely. Like cod, pollock ended a four-month winning streak in which its average price surged nearly 33%. The decline came even though import volumes are still well below normal, which hints at some demand destruction in the U.S. That needs to continue for prices to trend lower from here, because the pollock market usually doesn't peak for the year until Q4. Last year was an exception, but from 2018 through 2024, pollock hit its yearly high between October and December six times.
Outlook: Pollock will likely pick up seasonal support toward the end of 2026, so the best chance for a more meaningful price correction probably won't come until Q1 2027.
Past Reports
Commodities Report
Commodities Report
Commodities Report
Commodities Report
Menu Makers is a weekly tip series with the hottest and
most trendy menu items.
Click the play button on the left to watch the latest video,
or click the thumbnails below to review archived uploads.
Past Videos
Weekly Produce Reports
Weekly reports for all regions. Current conditions, market trends, historic projections, insider alerts – and all at your fingertips!
October 8, 2026 – Tomato production continues to decline out of South Carolina, Tennessee, and Virginia due to a combination of weather-related pressure and the season coming to a close. We will continue to see upward pressure on the markets this week, particularly Snacking Tomatoes, which …
Past Reports
Fresh Alliance Market Report
Weekly Commodity Reports
Detailed Commodity Reports and video Hot Takes from ArrowStream, for those in need of more in-depth reporting.
CommodityONE Market Report
In search of more detailed insight? Look no further than ArrowStream’s multi-page weekly CommodityONE Report.
Complete and submit the following form to receive your full report.
CommodityONE Hot Takes
Paul Savage, Director of Commodities at ArrowStream, presents the latest CommodityONE Hot Takes.
Click the play button to watch the latest video,
or click the thumbnails below to review archived uploads.
Past CommodityONE Updates
Step inside the foodservice world with Grounded, where we sit down with industry leaders to explore their personal journeys, business challenges, and big-picture perspectives from sourcing to service.
Hit play to watch the latest episode, or browse past conversations using the thumbnails below.
Foodservice Operator News
Check out insights and tips produced by experts from the Buyers Edge Platform family of brands.
- All
- Articles
- Data / Technology
- Digital Procurement Network / GPO
- Fresh Solutions / Fresh Division
- Supply Chain
Why Mashed Potatoes Belong on More Menus Across Foodservice
Source: Buyers Edge Platform
5 Ways Senior Living Procurement Software Improves Purchasing Decisions
Source: Prime Services
Restaurant Profit Margin: A Guide to Multi-Unit Operators
Source: Consolidated Concepts
Back to School Shopping Isn’t Just for Parents. Here’s What It Means for Convenience Stores
Source: SaveMore
Food Cost Problems and Their Impact on Profit Margins
Source: InsideTrack
Restaurant Profitability: How to Increase Margins and Reduce Costs
Source: Buyers Edge Platform
Hotel Restaurants Are Becoming Neighborhood Destinations. Is Your Procurement Strategy Ready?
Source: Source1
Stay up to date
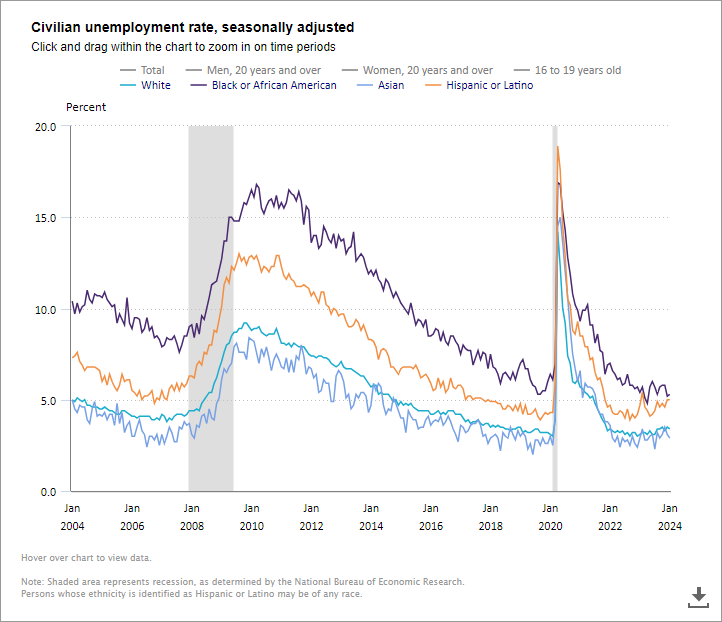
The Latest Facts & Figures
Live, interactive charts from industry experts
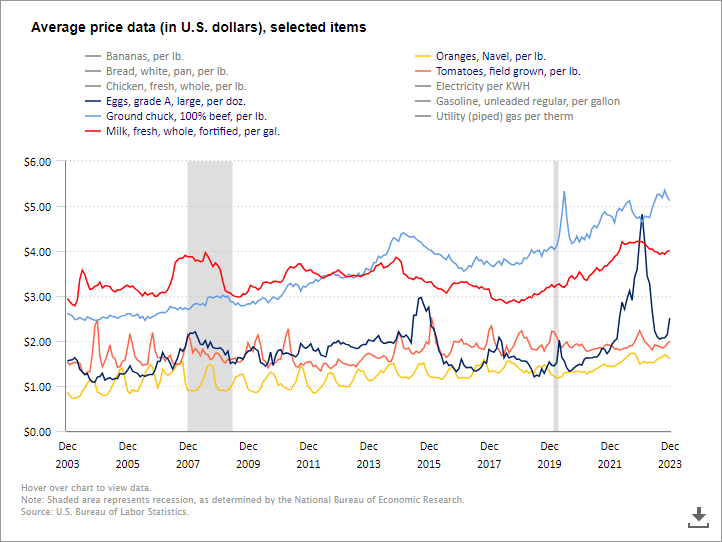
Click the thumbnails below to explore the latest data in each.
Then click the headings at the top to show or hide the different groups and categories.
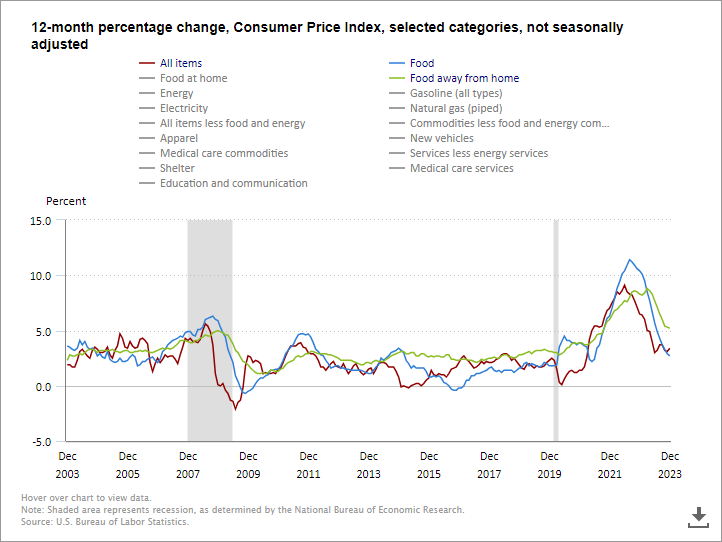
Consumer Price Index
Track the 12-month percentage changes of various goods and services.
Price Data
Track the price changes of key indicators including meat, produce and dairy.
Questions?
Contact our Team of Foodservice Experts
Submit this short form and an expert from the Buyers Edge Platform will reach back out to address your foodservice related questions or concerns.
Drop Us a Line
We will respond within 1-2 business days.